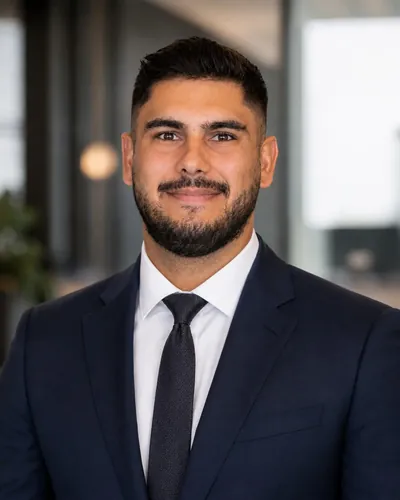
Mortgage broker in Saint-Lambert, on Montreal’s South Shore
Your next chapter.Well financed.
As your mortgage broker, I compare options from multiple lenders and guide you personally through the process, wherever you are in Quebec.
Book a free call30 minutes · No obligation
Estimate my mortgage payment →A network of over 30 lenders



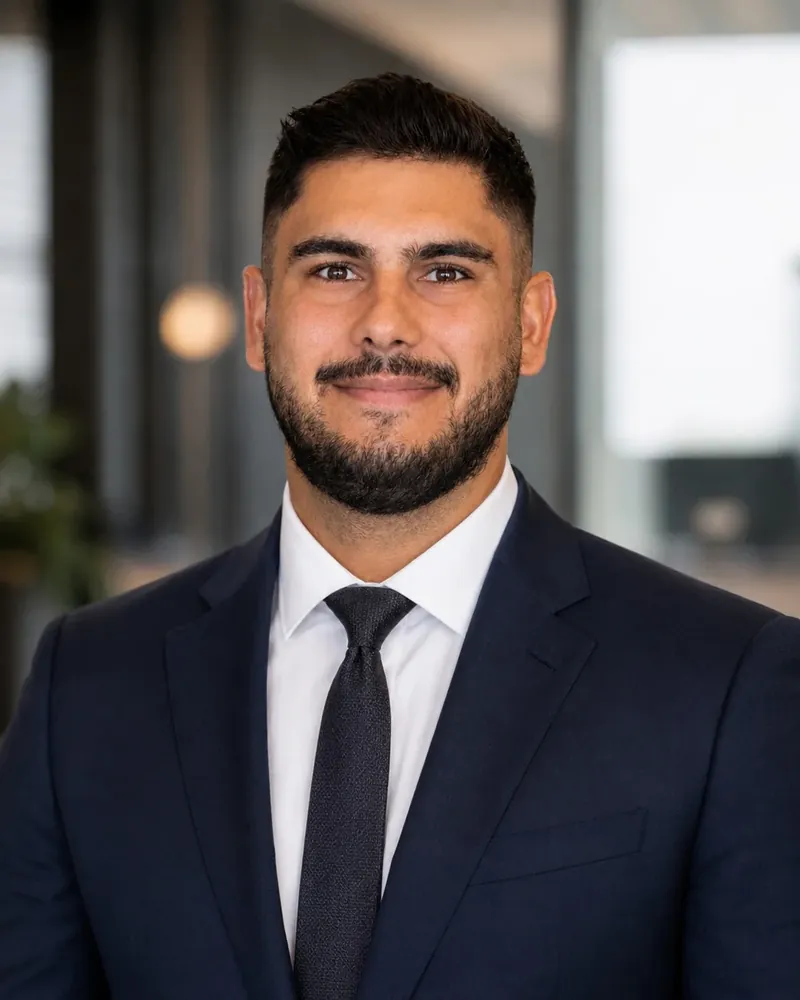
Jonathan Borsellino, mortgage broker affiliated with Groupe Kelto inc., under the Mortgage Architects banner.
What brings you here?
Your mortgage broker.
With you every step.
I studied finance at Concordia University and worked in commercial financing at National Bank. Today, I’m an independent mortgage broker with Groupe Kelto inc., under the Mortgage Architects banner, based in Saint-Lambert and serving clients throughout Quebec.
We’ll start with your budget and what matters to you. Then I’ll compare mortgage options, explain the differences and handle follow-up with the lender through to closing with the notary.
Let’s talk about your goals.
We’ll discuss your finances, your plans and what matters most to you.
I’ll compare your options.
I’ll explain the rates, terms and costs so you can make an informed decision.
I’ll guide you through the next steps.
From the paperwork to lender follow-up, I’ll help you understand what happens next.
My office
Saint-Lambert. South Shore.Across Quebec.
Based in Saint-Lambert, I help buyers and homeowners in Longueuil, Brossard, Montreal and across Quebec, by phone or video call.
Plan your first home purchase, your renewal or financing for a rental property.
Compare your mortgage options.
Enter your project details, then compare a second scenario if needed.
Scenario A
Accelerated payments add roughly one monthly payment per year to pay off your mortgage sooner.
- Principal repaid over the term
- Interest over the term
- Balance at the end of the term
- Total interest over the amortization period
- Mortgage before insurance premium
- Estimated CMHC insurance premium, added to mortgage
- Premium tax, paid separately
- Total mortgage amount
Scenario B
Accelerated payments add roughly one monthly payment per year to pay off your mortgage sooner.
Both scenarios use the same term.
Your comparison at a glance
| Detail | Scenario A | Scenario B |
|---|---|---|
| Your assumptions | ||
| Mortgage amount | — | — |
| Mortgage before premium | — | — |
| Insurance premium added to loan | — | — |
| Premium tax, paid separately | — | — |
| Annual interest rate | — | — |
| Payment frequency | — | — |
| Scheduled amortization | — | — |
| Term compared | — | — |
| Interest compounding | Semi-annual | Semi-annual |
| Payment per period | — | — |
| Over the selected term | ||
| Principal repaid | — | — |
| Interest paid | — | — |
| Total payments | — | — |
| Balance at the end of the term | — | — |
| Full amortization projection | ||
| Total interest at an unchanged rate | — | — |
B’s interest savings over the term
—Projected savings over amortization
—If each rate stays unchanged until the mortgage is paid off.A negative amount means higher interest costs for B.
Complete both scenarios to see the differences and print your comparison.
The loan amounts differ, so the difference in cost also reflects the amounts borrowed.
A lower payment does not necessarily mean a lower total cost. Full amortization results are projections: rates may change at renewal.
Discuss my scenariosThe estimated payment includes principal and interest. Budget separately for property taxes, insurance, maintenance and any condo fees. In insured purchase mode, the estimated premium is added to the mortgage; its tax is paid separately.
Illustrative estimate, not an offer. Taxes and insurance excluded. Eligibility depends on the lender.
Assumptions and sources
Illustrative fixed rate, compounded semi-annually and assumed unchanged over the entire amortization. Actual interest will vary at renewals.
Semi-annual compounding. Payments rounded up to the next cent, interest calculated without intermediate rounding, and a final payment adjusted to the balance. Payments at the end of each period. Accelerated options use the calculated monthly payment divided by 2 (26 payments per year) or by 4 (52 payments per year), then rounded up to the next cent. They add roughly one monthly payment per year and shorten the repayment period. Lender conventions may differ.
Your questions,
answered.
How much does it cost to work with you?
For most residential mortgages, you won’t pay me directly. I’m typically paid by the lender you choose. If any fees apply to your situation, I’ll explain them before we move forward.
Will this affect my credit?
Using the calculator or booking a call won’t trigger a credit check. A mortgage application may require one. Before proceeding, I’ll explain the type of check and how it could affect your credit.
How long does the mortgage process take?
Timing depends on the type of mortgage, the documents available, the property appraisal and the lender’s review. On our first call, we’ll discuss your timeline and what needs to be prepared.
What happens on our first call?
It’s a free, 30-minute conversation with no obligation. Tell me what you have in mind, ask your questions, and we’ll work out the next steps.
Do I have to switch banks?
Not necessarily. If staying with your current lender makes the most sense for you, I’ll say so.
Can we work together remotely?
Yes. I’m based in Saint-Lambert and work with clients throughout Quebec by phone or video call.
“Your project deserves
personal attention.”
Let’s talk about
your mortgage.
A free 30-minute call to discuss your plans.